Latest news today is that their net core income drop by 9%. I see that technically, the trend seems to be in bearish mode.
See more on the video;
Latest news today is that their net core income drop by 9%. I see that technically, the trend seems to be in bearish mode.
See more on the video;
GT Capital Holdings, Inc. (GTCAP) was incorporated on July 26, 2007 as a holding company. GTCAP is the primary vehicle for the holding and management of the diversified business interests of the Ty family in the Philippines. The Company holds interests in banking; automotive assembly, importation, distribution, and financing; property development; life and non-life insurance; and infrastructure and utilities.
GTCAP's subsidiaries are Federal Land, Inc.; Toyota Motor Philippines Corporation; Toyota Manila Bay Corp.; and GT Capital Auto Dealership Holdings, Inc. The Company also has significant shareholdings in Metropolitan Bank & Trust Company; Metro Pacific Investments Corporation; Philippine AXA Life Insurance Corporation; Toyota Financial Services Philippines Corporation; and Sumisho Motor Finance Corporation.

As of July 23, 2020, GTCAP was last traded at 438php per share, down by 55% compared to their 52-week high price. What valuation can we get from their March 2020 quarterly report?
Trailing P/E: 438/91.6= 4.8 Indicating that for every 1php income last 2019, investors are willing to pay or are paying 4.8php only. It is said that an overvalued company would be the one trading at a rate that’s 50 times earnings, or this could be a gauge on how optimistic are investors on this company. A lower P/E may imply low in optimism perhaps due to lower expectations on future earning, or news i.e pandemic that greatly impacts investor optimism.
For a growth rate of 56.9% change in EPS from 2018 to 2019, the PEG ratio would be 4.8/56.9=0.08 meaning, investors are paying 4.8php per earning relative to the growth rate of 56.9% from 2018 to 2019. A PEG ratio of less than 1 is usually considered undervalued.

Price to Book Value per share (P/B) = 438/760.14= 0.57, meaning, the current market price per share is 42.4% lower compared to the real worth of the company as based on their March 2020 financial report. A P/B of less than 3 is potentially undervalued
However, due to pandemic, their first 3 months net income dropped by 25.7%
Still, fundamentally, based on the parameters above, this share seems to be a good buy to accumulate.

However technically, the MACD seems to indicate bearish momentum. RSI also continues to move to an oversold level, it may be a good strategy to buy this stock while in a bearish mode as this will definitely bounce back. Caveat
Ayala Land, Inc. (ALI) was formerly the real estate division of Ayala Corporation (AC) and was incorporated on June 30, 1988 to focus on the development of its existing real estate assets. In July 1991, the Company became publicly-listed through an initial public offering of its primary and secondary shares on the Makati and Manila Stock Exchanges.
ALI is engaged in the planning and development of large scale, integrated estates having a mix of use for the sale of residential lots and buildings, office buildings and commercial and industrial lots, leasing of commercial and office spaces and the development, operation and management of hotels and resorts. The Company also develops commercial and industrial parks and is also engaged in property management, construction and other businesses like retail and healthcare.
Among the Company's subsidiaries are Alveo Land Corporation; Avida Land Corporation; Ayala Property Management Corporation; Makati Development Corporation; North Triangle Depot Commercial Corporation; Laguna Technopark, Inc.; and Ten Knots Philippines, Inc.

As of July 17, 2020, ALI was last traded at 31.7php per share, down by 3.65% from the previous trading. What valuation can we get from their March 2020 quarterly report?
Trailing P/E: 31.7/2.25= 14 Indicating that for every 1php income last 2019, investors are willing to pay or is paying 14php. It is said that an overvalued company would be the one trading at a rate that’s 50 times earnings, or this could be a gauge on how optimistic are investors on this company. A lower P/E may imply low in optimism perhaps due to lower expectation on future earning, or news i.e pandemic that greatly impact investor optimism.
For a growth rate of 13.6% change in EPS from 2018 to 2019, the PEG ratio would be 14/13.6=1 meaning, investors are paying 14php relative to the growth rate of 13.6% from 2018 to 2019. A PEG ratio of less than 1 is usually considered undervalued, in this case, the market price seems to be just right relative to growth rate
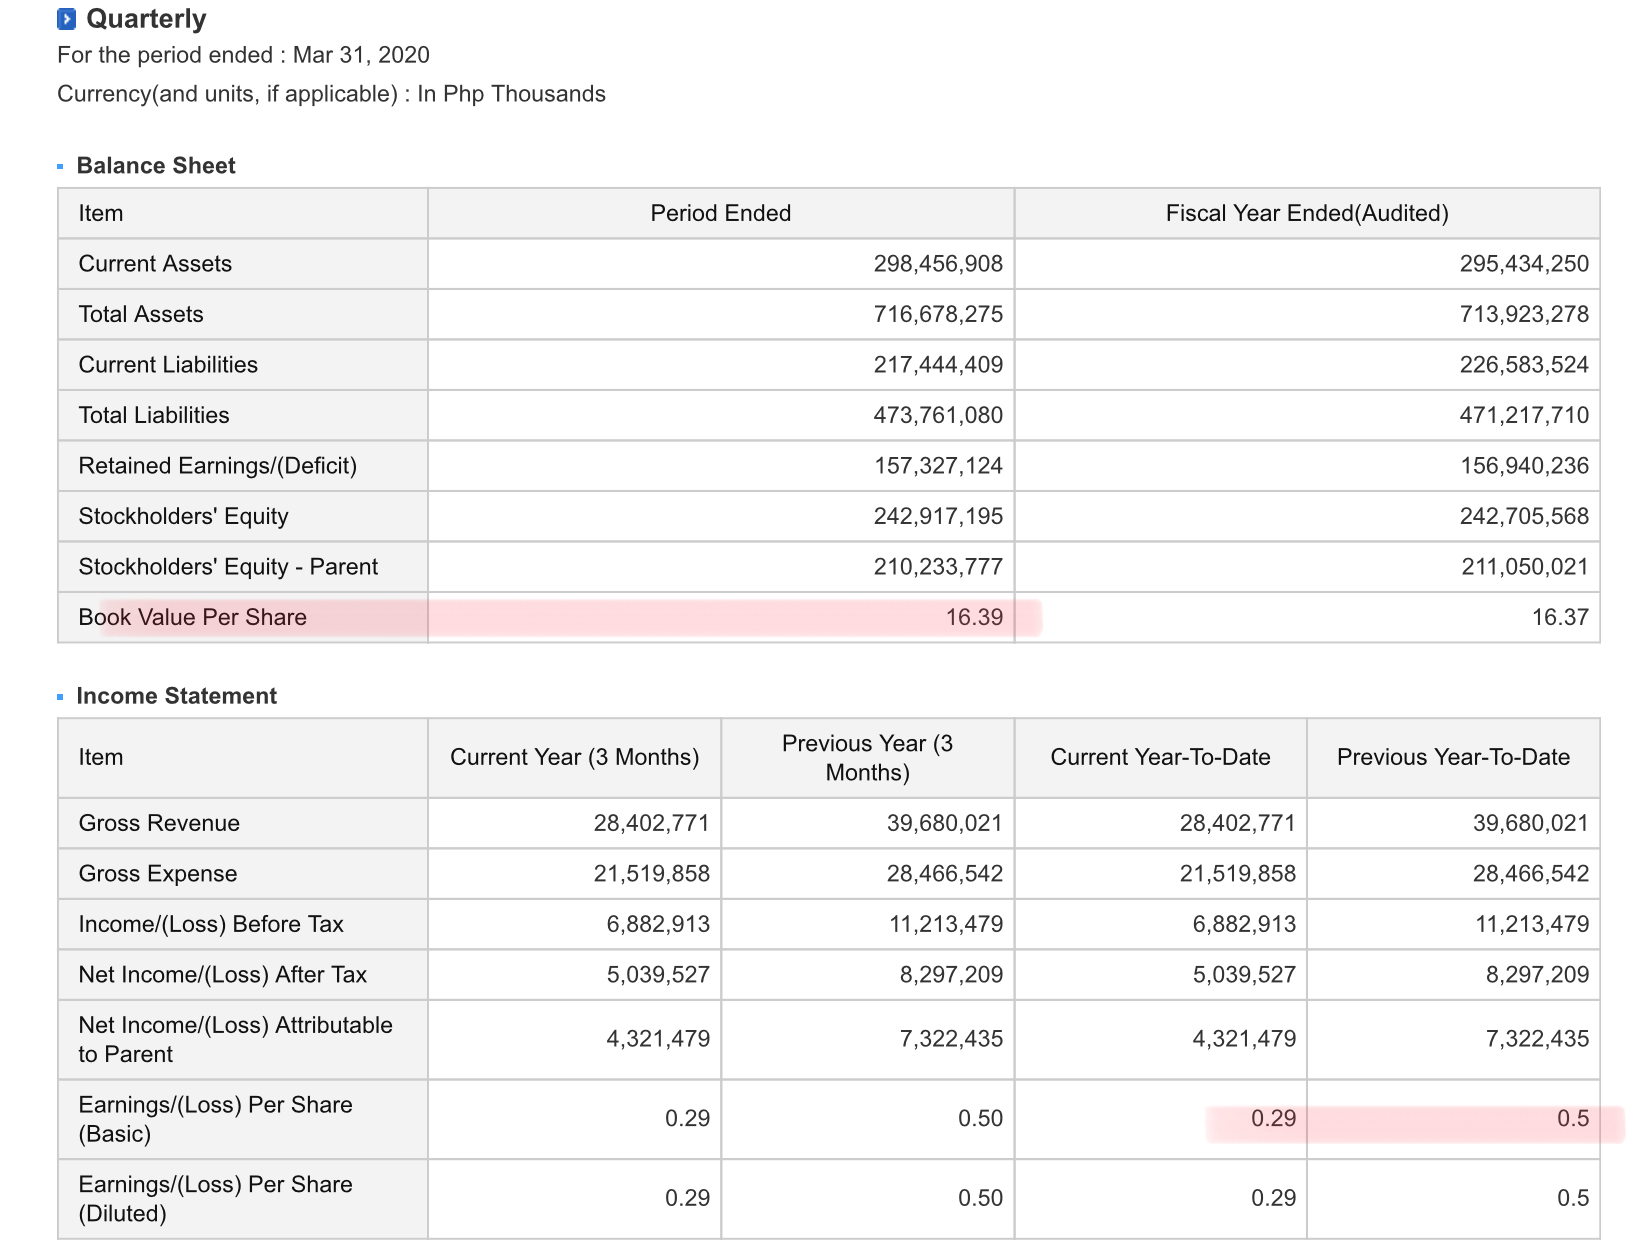
Price to Book Value per share (P/B) = 31.7/16.39= 1.9, meaning, the current market price per share is around 1.9 times higher compare to the real worth of the company as based on their March 2020 financial report. A P/B of less than 3 is potentially undervalued.
However, due to pandemic, their first 3 months net income dropped by 41%, still fundamentally, based on the parameters above, this share seems to be a good buy.

However technically, the MACD seems to indicate a bearish momentum. RSI also continues to move to an oversold level. If I’m to buy this share, I’ll wait few more trade to see whether the momentum has a sign of reversal to bullish mode.
Disclaimer: Trade or invest at your own risk.
East West Banking Corporation (EW) was registered with the Securities and Exchange Commission on March 22, 1993. The Company was granted authority by the Bangko Sentral ng Pilipinas (BSP) to operate as a commercial bank in 1994 and commenced operations on July 8 of the same year.
EW's principal banking products and services include deposit-taking, loan and trade finance, treasury, trust services, credit cards, cash management and custodial services. The Company offers the financial services to consumer and corporate clients. On January 25, 2012, EW obtained from BSP the approval to operate as a universal bank.
On May 6, 2016, EastWest and Standard Chartered Bank Philippines (SCB PH) entered into an agreement for SCB PH’s retail business. Under the agreement, the credit cards, personal loans, wealth management and deposits of SCB in the Philippines will be migrated to EastWest.
The Company's wholly-owned subsidiaries are East West Rural Bank, Inc.; East West Insurance Brokerage, Inc.; Quest Marketing and Integrated Services, Inc.; East West Leasing and Finance Corporation, and Assurance Solutions Insurance Agency. EW also owns 50% of East West Ageas Life Insurance Corporation, a life insurance firm formed with Ageas Insurance International N.V.
As of December 31, 2018, EW has a network of 390 branches and 583 automated teller machines, majority of which are located within Metro Manila.

As of July 15, 2020, EW was last traded at 7.37php per share. What valuation can we get from their March 2020 quarterly report?
Trailing P/E: 7.37/2.77= 2.6 Indicating that for every 1php income last 2019, investors are willing to pay or is paying 2.6php only. It is said that an overvalued company would be the one trading at a rate that’s 50 times earnings, or this could be a gauge on how optimistic are investors on this company. A lower P/E may imply low in optimism perhaps due to lower expectation on future earning, or news i.e pandemic that greatly impact investor optimism.
For a growth rate of 38.5% change in EPS from 2018 to 2019, the PEG ratio would be 2.6/38.5=0.06 meaning, investors are paying 2.6php relative to the growth rate of 38.5% from 2018 to 2019. A PEG ratio of less than 1 is usually considered undervalued.

Price to Book Value per share (P/B) = 7.37/22.74= 0.3, meaning, the current market price per share is 67.5% lower compare to the real worth of the company as based on their March 2020 financial report. A P/B of less than 3 is potentially undervalued
In spite of pandemic, their first 3 months net income increase by 74.7%.
Fundamentally, based on the parameters above, this share seems to be a good buy to accumulate. Once the pandemic is over, this share will eventually catch up to its real worth.
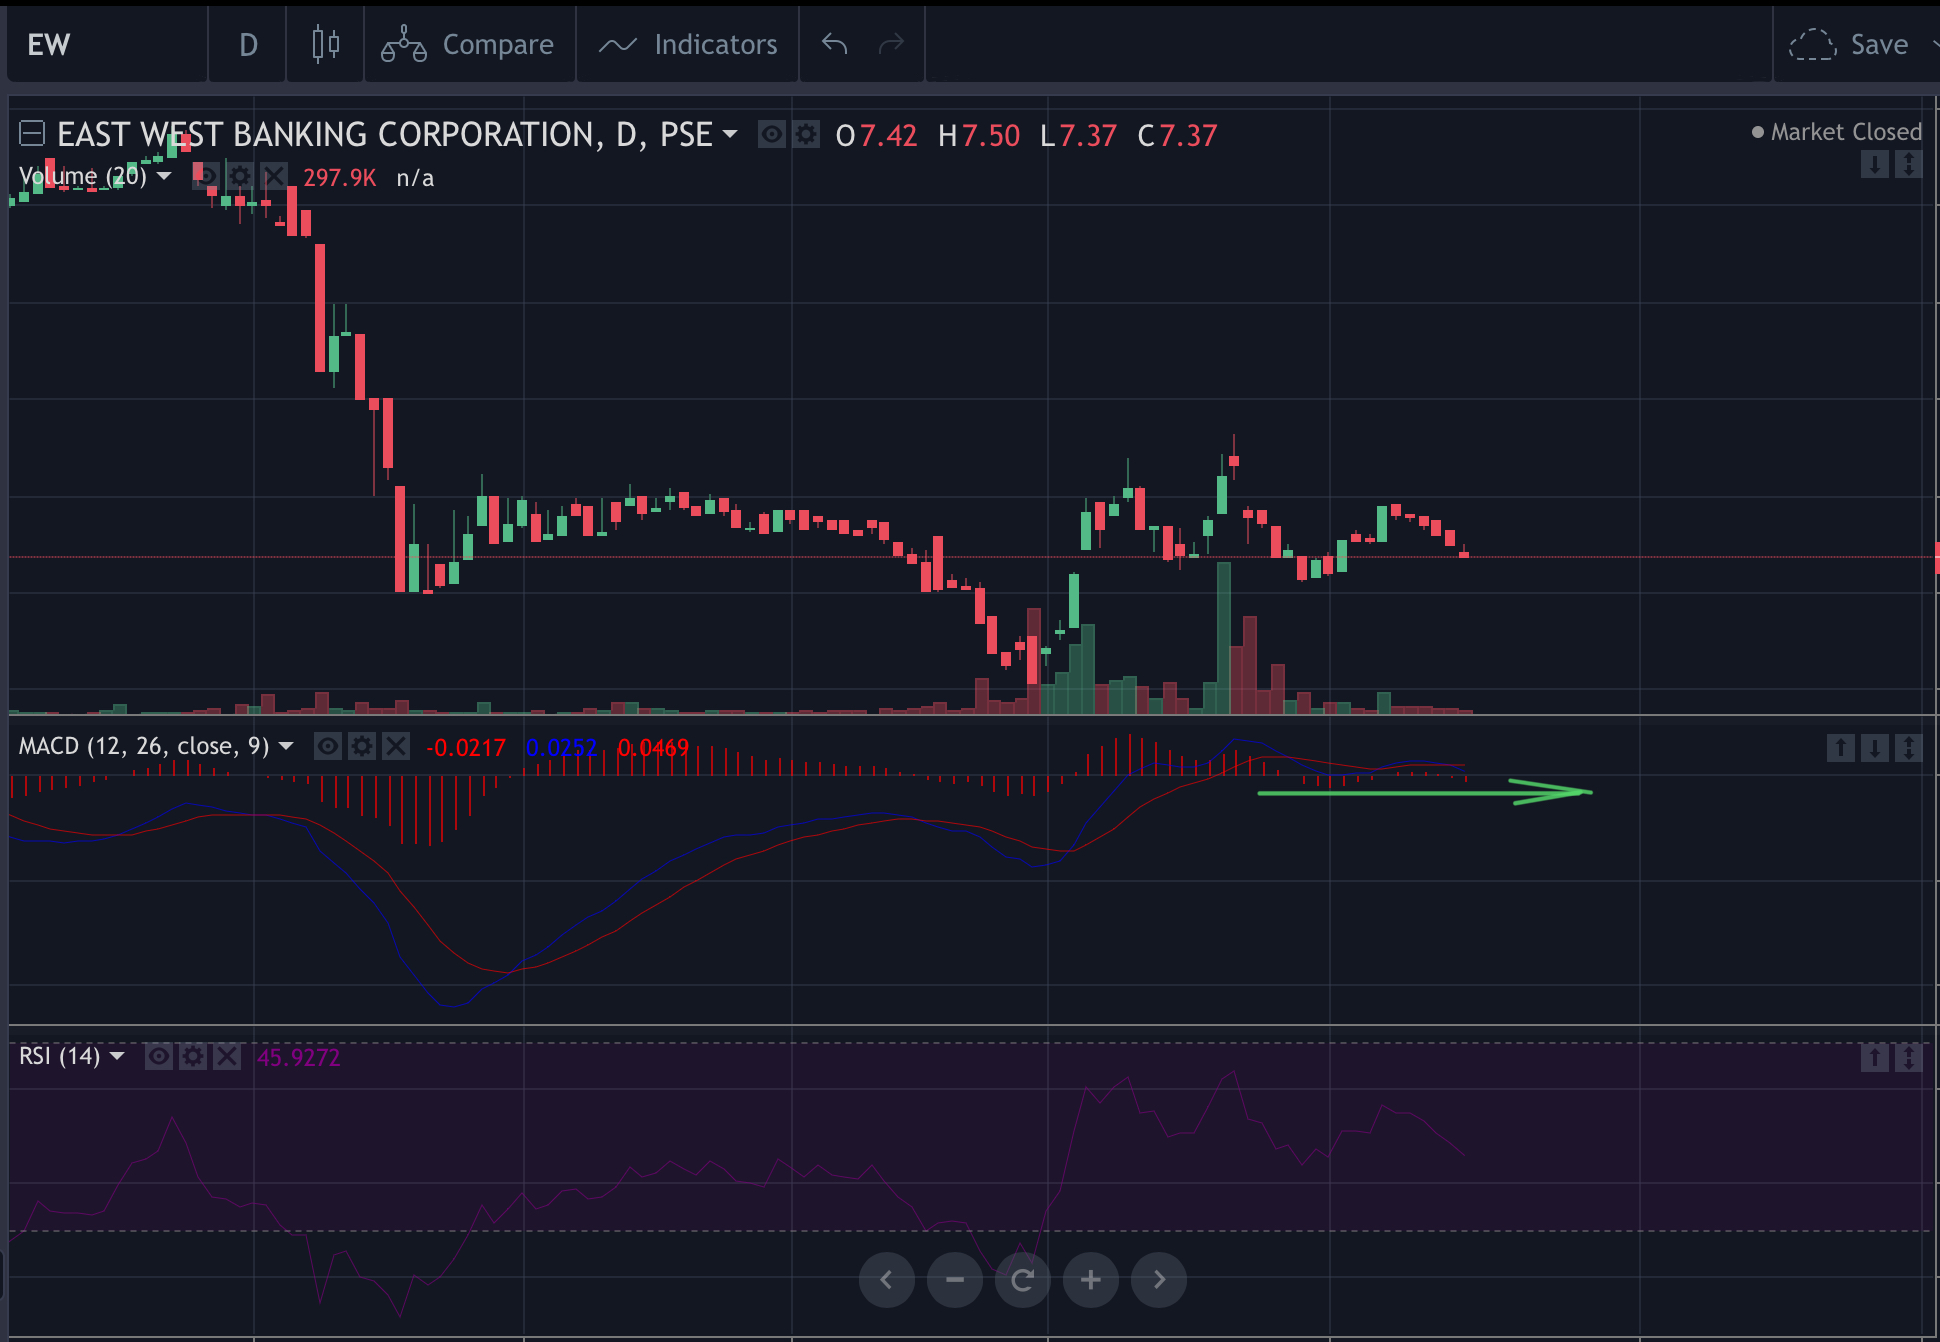
However technically, the MACD histogram seems to indicate a sideway momentum. If you are into longterm investing, I suggest you accumulate this share.
Disclaimer: Trade or invest at your own risk.
First Gen Corporation (FGEN) was incorporated and registered with the Securities and Exchange Commission on December 22, 1998. FGEN and its subsidiaries are involved in the power generation business. FGEN is the largest clean and renewable Independent Power Producer in the Philippines, with a total installed capacity of 3,490 MW as of December 31, 2018.
The Company owns power plants which utilize natural gas, geothermal, wind, hydro and solar power, all of which are operational and majority-owned and controlled by the Company through its subsidiaries. These subsidiaries include First Gas Power Corporation, FGP Corp., First NatGas Power Corp., Prime Meridian Powergen Corporation, FG Bukidnon Power Corporation, and Energy Development Corporation.
As of December 31, 2018, First Philippine Holdings Corporation directly and indirectly owns 66.98% of the common shares of FGEN and 100% of FGEN's voting preferred shares. Lopez, Inc. is the ultimate parent company of FGEN.

As of July 6, 2020, FGEN was last traded at 25.7php per share or 0.52USD. What valuation can we get from their March 2020 quarterly report?
Trailing P/E: 0.52/0.07= 7.4 Indicating that for every 1USD income last 2019, investors are willing to pay or is paying 7.4USD. It is said that an overvalued company would be the one trading at a rate that’s 50 times earnings, or this could be a gauge on how optimistic are investors on this company. A lower P/E may imply low in optimism perhaps due to lower expectation on future earning.
For a growth rate of 40% (change in EPS from 2018 to 2019), the PEG ratio would be 7.4/40=0.19 meaning, investors are paying 7.4USD relative to the growth rate of 40% from 2018 to 2019. A PEG ratio of less than 1 is usually considered undervalued.

Price to Book Value per share (P/B) = 0.52/0.61= 0.8, meaning, the current market price per share is 14.7% lower compare to the real worth of the company as based on their March 2020 financial report. A P/B of less than 3 is potentially undervalued
The first 3 months net income dropped by 19.6%.
Fundamentally, based on the parameters above, this share seems to be a good buy.

However technically, the MACD histogram seems to indicate a decline in momentum prompting profit taking. Meanwhile, RSI also already reach the overbought level signalling a downward momentum
Disclaimer: Trade or invest at your own risk.
MerryMart Consumer Corp. (MM), formerly Injap Supermart Inc., is a consumer-focused retail company principally engaged in the operation of retail stores in the supermarket and, beginning January 30, 2020, household essentials category. MM, through its subsidiary, MerryMart Grocery Centers Inc. (MMGC) intends to pioneer the franchise business model covering supermarkets and household essentials stores in the Philippines (collectively, MM and its subsidiary, MMGC, are known as the 'MM Group').
Currently, the MM Group owns and operates seven MM branches nationwide, with an aggregate selling space of 9,331 square meters. The MM Group aims to open six more MM branches by the second quarter of 2020, six additional branches by the third quarter of 2020, and have a total of 100 branches located all over the Philippines by the fourth quarter of 2021.
MM is a wholly-owned subsidiary of Injap Investments Inc., which also owns 35% of DoubleDragon Properties Corp.

As of July 2, 2020, MM was last traded at 3.29php per share. This company was recently listed last June 15, 2020, and released their first quarter report the other day. What valuation can we get from their March 2020 quarterly report?
Trailing P/E = 3.29 / 0.03 = 109.6 Indicating that for every 1php income last 12 months, investors are willing to pay or is paying 109.6php. It is said that an overvalued company would be one trading at a rate that’s 50 times earnings, or it could be an optimism whereby investors expect earnings growth in the coming quarters and, as a result, investors have been buying the stock in anticipation of its appreciation. MM nature of business is like of that PGOLD and RRHI which are companies that are already established, the P/E’s of these companies are below 20, yet MM P/E is above 100. Having said this, I say that the expectation is a bit much, thus it’s potentially overvalued.
Price to Book Value per share (P/B) = 3.29 / 0.07 = 47, meaning, the current market price per share is 47 times higher that the real worth of the company as based on their March 2020 financial report. A P/B of more than 3 is potentially overvalued.
Even though the net income for the first 3 months this year increased by 50.5% from the last year first 3 months, still, based on the P/E comparing it with established companies, the current price seems to be not justified, not to mentioned the P/B ratio.
Disclaimer: Trade or invest at your own risk.
BDO Unibank Inc. (BDO), originally known as Acme Savings Bank, was acquired by the SM Group in 1976. BDO listed its shares on the Philippine Stock Exchange on May 21, 2002. The Company merged with Equitable PCI Bank in May 2007.
BDO offers an array of products and services, i.e. retail banking; lending (corporate, commercial, consumer, and SME); treasury; trust; credit cards; corporate cash management; and remittances. Through its subsidiaries, the Company offers leasing and financing; investment banking; private banking; bancassurance; insurance brokerage; and stock brokerage services.
The Company's local subsidiaries include BDO Private Bank, Inc.; BDO Leasing and Finance, Inc.; BDO Capital & Investment Corporation; BDO Nomura Securities, Inc.; and BDO Insurance Brokers, Inc. The Company also has foreign subsidiaries in the US, Hong Kong, Italy, Japan, Canada, and Macau. The Company's associates include NLEX Corporation; SM Keppel Land, Inc.; Northpine Land Inc.; Taal Land, Inc.; and MMPC Auto-Financial Services Corporation.
As of December 31, 2018, BDO has 1,309 operating domestic branches (inclusive of one branch each in Hong Kong and Singapore), 4,325 automated teller machines and 484 cash deposit machines.

As of June 29, 2020, BDO was last traded at 94PHP per share. Its market price is 41.9% lower from its 52 week high. Is this fundamentally cheap and technically time to buy?
Trailing P/E = 9.4 Indicating that for every 1php income last 2019, investors are willing to pay 9.4php.
Trailing PEG Ratio = 0.3, meaning, investors are willing or is paying 9.4php for every peso income last 2019 relative to growth growth rate of 35.4% which is the change of EPS from 2018 to 2019. A PEG ratio of less than 1 is considered undervalued.

Price to Book Value per share (P/B) = 1.1, meaning, the current market price per share is just 1.1 times higher that the real worth of the company as based on their March 2020 financial report. Usually, a P/B of less than 3 is considered undervalued.

Technically, the MACD momentum is in selling signal. RSI also is indicating a continuation of selling. If I’m the investor, I would wait first for a sign of momentum reversal and not enter yet, but fundamentally, this is a good stock to accumulate.
Disclaimer: Trade or invest at your own risk.

The significant subsidiaries of AC as of December 31, 2018, are Ayala Land, Inc.; Manila Water Company, Inc.; Integrated Micro-Electronics, Inc.; AC Energy, Inc.; and AC Industrial Technology Holdings Inc.

As of June 17, 2020, AC was last traded at 790.5PHP per share. The company is one of the PSE index company and top gainers from yesterday’s trading. Its market price dropped by at least 20% from its 52 week high, largely because of the COVID19 pandemic. But is it now fundamentally cheap to buy?
In terms of P/E, AC recorded a trailing P/E of 14.6, meaning, for every 1PHP earning last 2019, investors of this company are willing or are paying 14.6Php. With 14.6 P/E and with a growth rate of 10.9% (change in EPS) from 2018 to 2019, the company trailing PEG ratio would be 0.36 which would be considered undervalued, typically, a PEG ratio of less than is in the category of undervalued.

In terms of price to book value per share, the current market price is currently 1.6 times higher than the book value as recorded in their March 2020 financial report, meaning, the company is perceived to be just 1.6 times higher compared to the real worth of the company. In terms of this parameter, It’s also undervalued, typically, PBV of less than 3 is considered undervalued.
In terms of income, as per their March 2020 financial statement, expectedly, it dropped by 17%.
Is this a good stock to accumulate fundamentally in this pandemic period? Based on the parameters above, it suggests that it’s fundamentally cheap to buy in this period.
Disclaimer: Trade or invest at your own risk.

In 2003, the Company received a license from the Philippine Amusement and Gaming Corporation (PAGCOR) to launch e-Games Stations, which are Internet cafes exclusively dedicated to casino games. With technology provided by WEB, patrons can choose from more than 300 casino games, including baccarat, blackjack, various slot machine games, video poker and sports betting. There are currently 288 operating e-Games cafes across the country, majority of which are owned and operated by independent operators.
WEB’s subsidiaries include BigGame, Inc.; e-Magine Gaming Corporation; PhilWeb Asia-Pacific Corporation; Major Games and Amusement Corporation; and PhilWeb Mobile Lottery Corp., among others.

As of June 15, 2020, WEB was last traded at 2.36php per share. Its market price dropped by at least 50% from its 52 week high, largely because of the COVID19 pandemic, but is it now fundamentally cheap to buy?
In terms of P/E, WEB recorded a negative trailing P/E of 33.7, meaning, for every 1php earning last 2019, investors of this company are willing or is paying negative 33.7. With a negative P/E and with a negative growth rate (change in EPS) from 2018 to 2019, the company trailing PEG ratio would also be negative, which would be overvalued.

In terms of book value per share, the current market price is currently 11.8 times higher than the book value as recorded in their March 2020 financial report, meaning the company is perceived to be 11.8 times higher compare to the real worth of the company. In terms of this parameter, it’s also overvalued
In terms of income, as per their March 2020 financial statement, they also have a negative income.
Is this a good stock to accumulate fundamentally in this pandemic period? Obviously not, this is a stock being traded technically disregarding the fundamental value.
Disclaimer: Trade or invest at your own risk.


