Showing posts with label Money. Show all posts

Wednesday, June 10, 2020

How expensive SMPH fundamentally based on their March 2020 financial report?

SM Prime Holdings, Inc. (SMPH) was incorporated on January 6, 1994 to acquire and develop real estate, conduct and maintain commercial shopping centers including shopping center spaces for rent, amusement centers, movie or cinema theaters, and to construct and manage buildings such as condominium, apartments, hotels, restaurants, stores and other structures for mixed use purposes. The Company has now four business units, namely, malls, residential, commercial, and hotels and convention centers.

As of December 31, 2018, SMPH has 72 malls in the Philippines and seven shopping malls in China. The malls in China are located in the cities of Xiamen, Jinjiang, Chengdu, Zibo, Chongqing, Tianjin, and Suzhou. The Company has 44 residential projects, 13 commercial projects, six hotels, four convention centers and three trade halls. SMPH also owns Sky Ranch, an amusement park in Tagaytay City and within SM City Pampanga.

Among the Company's subsidiaries are SM Development Corporation; Costa del Hamilo, Inc.; Highlands Prime Inc.; Tagaytay Resort Development Corporation; SM Arena Complex Corporation; SM Hotels and Conventions Corp.; and SM Land (China) Limited.

As of June 9, 2020, SMPH was last traded at 33.5php per share. SMPH is one of the listed company. Its market price dropped by at least 20% from its 52 week high, largely because of the COVID19 pandemic, but is it now fundamentally cheap to buy?


In terms of P/E, SMPH recorded a trailing P/E of 25.38, meaning, for every 1php earning last 2019, investors of this company are willing or is paying 25.38php. With a 25.38 P/E and with a growth rate of 17.8% (change in EPS) from 2018 to 2019, the company trailing PEG ratio would be 1.42, which would be considered a bit of overvalued. A PEG ratio that is more than 1 is generally considered as overvalued.

In terms of book value per share, the current market price is currently 3.2 times higher than the book value as recorded in their March 2020 financial report, meaning the company is still perceived to be 3.2 times higher compare to the real worth of the company. It seems in terms of this parameter, it’s still overvalued

In terms of income, as per their March 2020 financial statement, expectedly due to COVID19 dropped by 5.4%.

Is this a good stock to accumulate fundamentally in this pandemic period? Based on the indicators above, it seems not good since even though the price dropped, it is still under the range of overvalued.

Disclaimer: Trade or invest at your own risk.

Sunday, December 10, 2017

Interested to have a Laundry business where you can monitor wherever you are in details?

Almost there. To God be all the Glory.

Want to own a laundry business where you can monitor in details without you being physically present? Perfectly ideal for OFW.

What you will be able to monitor daily in details.

  • Actual Sales Per Day
  • Actual Realised Sales Per day
  • Kilos of laundry and dry cleaned per day
  • Expenses amount and details, Accumulated expenses from the day you start the business.
  • Records of the customer, when and how many times they came back. Their accumulated kilos, the ref receipt no.
  • Customers who have yet to pay.
  • The actual money the business is holding daily. (You’ll know on a daily basis whether there is a discrepancy between how much money the shop reported and how much money the shop should have).
  • Needed amount to compensate all future expenses.
  • Days of operation, staff schedule, and many others.

The best part, if you are already versatile with the business system, you’ll be able to update the above details for utmost 1 hour only anywhere you are as long as long as you have a laptop with excel on it, it won’t affect your day job.

The one thing I learned and foresaw was that, if you are to venture into business, start early while you are still working because, in starting a business, there are so many unknown factors which you will only able to realized along and while in the process. You can theorize and everything but, I can assure you that what actually might happen is not what you expected. Having the day job and by starting early, you'll have something to fall back and have time to recuperate. In fact, your day job might be the key for the business to be successful as most of those unknown factors need funding, this is where your day job comes in. The system in place will also help you decide whether it's futile or just a waste of time and money to keep going, it will help you decide to finally use the fallback plan to start recuperating or go on as you see the business potential. You can also use the data from the system to strategize on the marketing approach and you'll be able to know whether the strategy works or not as you'll see the charts whether it improves or not. From there, you'll be able to deduce the potential of the business.

Comment and or email me at sherwincablao@gmail.com for those who are interested.

Sunday, October 8, 2017

How Expensive is Metro Pacific Investment (MPI) now fundamentally based on their June 2017 Quarterly Report?

Metro Pacific Investments Corporation (MPI) was incorporated on March 20, 2006 as an investment holding company. The Company is organized into the following segments based on services and products: water; toll roads; power generation and distribution; healthcare services; light rail and logistics.

The Company's subsidiaries are Maynilad Water Holding Company, Inc.; Metro Pacific Tollways Corporation; Manila Electric Company; Metro Pacific Hospital Holdings, Inc.; Metro Pacific Light Rail Corporation; and MetroPac Logistics Company, Inc.

As of December 31, 2016, MPI's investments outside the Philippines include an effective ownership of 29.4% in DMT, a Thai toll road operator, and 45.0% in CII B&R, a toll road company located in Ho Chi Minh City in Vietnam.


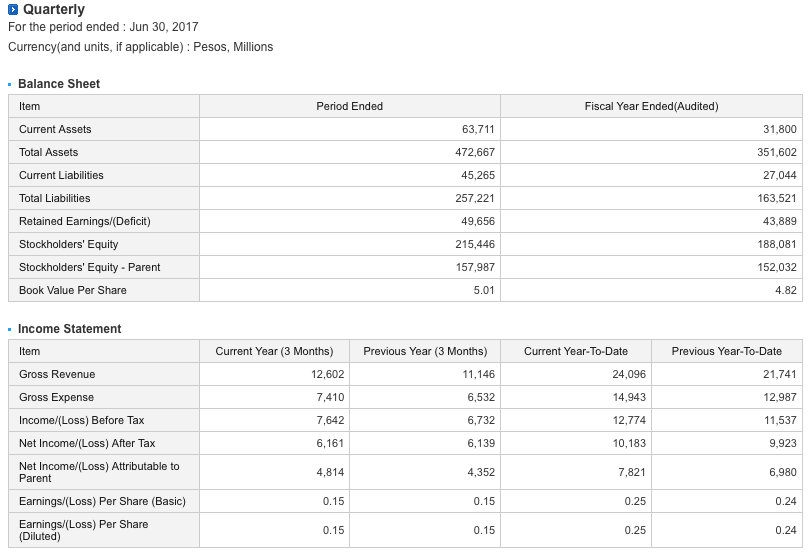
As of Oct 06, 2017, MPI was last traded price at 6.88Php. This is just 1.37 times higher compared to their recorded book value as according to their June 2017 quarterly report. In terms of this parameter, a value investor may find the market price to be still acceptable. 

In terms of P/E, the company recorded a trailing P/E of 18.11 meaning, for every 1PHP earning last 2016, investors of this company are willing or is paying 18.11Php. In terms of P/E, it seems like it's still in the not expensive range but, let us take a look further on the company PEG ratio. With the P/E value and with a growth rate of just 11.76% from 2015 to 2016, the company trailing PEG ratio would be 1.54 which means, investors of this company are paying 18.11Php for every 1PHP income last 2016 for a growth rate of 11.76%. In terms of this parameter, a value investor may find this share to be a bit overvalued since the PEG ratio is already more than 1. Fair value stocks usually have a P/E that is equal to the growth rate.

In terms of income, the first 6 months net income attributable to parent this year increases by 12.05% in comparison to last year first 6months net income but the EPS grows only by 4%. Why is this? Well, perhaps part of the increase in income was due to the issuance of an additional share which was converted into income. 

Disclaimer: Trade or invest at your own risk.

<P.S> Are you in Singapore? Confused and hardly able to understand what I'm talking about? Message me on facebook. 

Monday, October 2, 2017

How Expensive is Crown Asia Chemical Corp (CROWN) now fundamentally based on their June 2017 Quarterly Report?

Crown Asia Chemicals Corporation (CROWN) was incorporated and registered with the Securities and Exchange Commission (SEC) as Crown Asia Compounders Corporation on February 10, 1989 primarily to engage in, operate, conduct, and maintain the business of manufacturing, importing, exporting, buying, selling or otherwise dealing in, at wholesale and retail such goods as plastic and/or synthetic resins and compounds and other allied or related products of similar nature. On September 29, 2014, the SEC approved the change of the Company’s name to the present one.

In 1998, the Company began the production of PVC flexible electrical pipes. Soon after, the Company’s range of product lines expanded further with the introduction of PVC electrical conduit pipes and potable water pipes in 2000, and sanitary pipes and fittings in 2002. In 2003, the Company started to develop and market PVC compounds for use in integrated circuit (IC) packaging tubes, films and bottles, as well as door and window profiles. In 2006, CROWN explored the HDPE market by engaging in marketing and trading HDE pipes and fittings, which were supplied by and HDPE pipes manufacturer and importer. In November 2013, the Company started manufacturing its own HDPE pipes.

At present, CROWN is engaged in the production of plastic compounds, plastic pipes and other related products such as polyvinyl chloride (PVC) pellets, which are used directly and indirectly in the construction and telecommunications industries. The Company derives its revenues from the operations of its two business groups, namely, the compounds group and the pipes group. CROWN sells its compounds to manufacturers of wires and cables, IC tubes, films and sheets, and bottles, among others, while of pipes are sold to hardware dealers, wholesalers, and distributors and to bidded construction projects. 

The Company’s products are located in Guiguinto, Bulacan and in its Davao branch.


As of Sept 29, 2017, CROWN was last traded price at 1.93Php. This is just 1.25 times higher compared to their recorded book value as according to their June 2017 quarterly report. In terms of this parameter, a value investor may find the market price to be still acceptable. 

In terms of P/E, the company recorded a trailing P/E of 10.7 meaning, for every 1PHP earning last 2016, investors of this company are willing or is paying 10.7Php. In terms of P/E, it seems like it's not yet expensive but, let us take a look further on the company PEG ratio. With the P/E value and with a growth rate of just 5.88% from 2015 to 2016, the company trailing PEG ratio would be 1.8 which means, investors of this company are paying 10.7Php for every 1PHP income last 2016 for a growth rate of only 5.88%. In terms of this parameter, a value investor may find this share to be overvalued since the PEG ratio is already more than 1.

In terms of income, the first 6 months net income after tax this year increases by 4.9% in comparison to last year first 6months net income.

Disclaimer: Trade or invest at your own risk.
<P.S> Are you in Singapore? Want to learn how to read stocks fundamentally? PM me on my fb page.

Sunday, September 10, 2017

Know Your Stocks - How Expensive is Cosco Capital. (COSCO) fundamentally based on their June 2017 Quarterly Report?

Cosco Capital Inc. (COSCO), formerly Alcorn Gold Resources Corporation, was originally incorporated on January 19, 1988 with the primary purpose of engaging in exploration, development, and production of oil and gas, and metallic and non-metallic reserves in partnership with other companies or in its individual capacity. On January 13, 2000, the Securities and Exchange Commission (SEC) approved the amendment of the Company's primary purpose from an oil and mineral exploration and development corporation into a holding company.

On April 12 2013, Lucio L. Co. Group (LLCG) and COSCO executed a Deed of Agreement in payment for the subscription wherein the LLCG shall subscribe to the unissued unauthorised capital stock of the Company. Ten (10) days later, the SEC approved the change in corporate name to the present one.

COSCO, as a holding company, currently has a portfolio comprised of interests in retail, real estate and property leasing, liquor distribution, oil and mining, and specialty retail. The Company's retail interests include Puregold Price Club, Inc. and S&R Membership Shopping. COSCO’s real estate and property leasing interests include Ellimac Prime Holdings, Inc., Fertuna Holding Corporation, Patagonia Holdings Corp., Nation Realty, Inc., 118 Holdings, Inc., NE Pacific Shopping Centers Corporation, and Pure Petroleum Corp. The interests of the Company in Liquor distribution include Montosco Inc., Meritus Prime Distributions, Inc., and Premier Wine and Spirits, Inc. The Company’s oil and mining interests include Alcorn Petroleum and Minerals Corporation. In specialty retail, COSCO’s interests include Liquigaz Philippine Corporation and Office Warehouse, Inc.


As of 8th of September 2017, COSCO was last traded price at 8.1PHP. This is 23.3% lower compared to their recorded book value as of June 2017 quarterly report. In terms of this parameter, it's possibly undervalued since the company net worth is more than the market price.

In terms of P/E, the company recorded a trailing P/E of 12.2 meaning, for every 1PHP earning last 2016, investors of this company are willing or is paying 12.2PHP only. With a 12.2 P/E and with a growth rate (change in EPS) of 6.4% from 2015 to 2016, the company trailing PEG ratio would be 1.9 which is more than 1.0 meaning, investors of this company are paying 12.2PHP for every 1PHP income last 2016 even if the company grows only by 6.4% from 2015 to 2016.

In terms of income, the first 6 months net income attributable to parents increases by 5.4% in comparison to last year first 6 months net income.

Disclaimer: Trade or invest at your own risk.

Advertisement

Advertisement
Click the picture to be redirected to facebook page